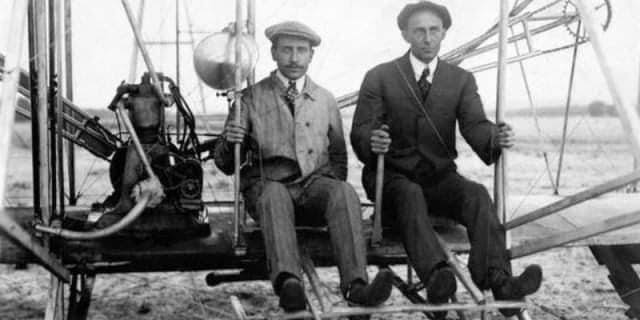
 In 1938 the airline business was brand new – only 35 years had passed since the Wright brothers’ first flight at Kitty Hawk.
Hardly anyone had even seen an airplane. A coast-to-coast round trip cost about $260, half the price of a new car, so passengers were mostly very wealthy.
The airlines were small, and during the Depression they were losing money. Congress was afraid they would undercut each other into bankruptcy, and the country would lose an industry it needed for its mail and its defense.
So lawmakers created the agency that became the Civil Aeronautics Board. For the next forty years, the Board set the airfare on every interstate route in America. They even decided which airlines were allowed to fly those routes.
The idea was well intended; they viewed airlines as an element of national security that needed protection.
But whatever good intentions the Board started with, by the 1970s it was just a soulless bureaucracy that stifled competition and said “no” to everything new.
An airline that wanted to CUT its prices needed the Board’s permission. So did anyone who wanted to start a new major airline.
Between 1950 and 1974, 79 new airlines applied to the Board. Zero were approved.
The consequences were obvious; remember, the Board only regulated interstate routes, so the public could see the difference.
For example, in 1965, a California airline called PSA flew Los Angeles to San Francisco for $11.43. Because the route was within the state, it was unregulated.
Meanwhile, the cheapest ticket from Boston to Washington— about the same distance, but across state lines and hence regulated by the Board – was $24.65.
In other words, federal regulation more than doubled the fare.
By the late 1970s Americans were hurting. The Arab oil embargo of 1973 had nearly quadrupled the price of oil, which stayed high. It was the decade of stagflation: prices had nearly doubled in ten years, inflation was running near 9% by the fall of 1978.
President Jimmy Carter was looking for anything he could do to bring prices down.
He understood that more competition means lower prices. “Of all our weapons against inflation,” he told the country in a televised speech on October 24, 1978, “competition is the most powerful.”
That same day he signed a law phasing the Board out, and by 1985 it no longer existed.
Sure enough, within six years the average airfare had fallen, even though inflation was still raging elsewhere in the economy.
And this was Jimmy Carter… hardly a free market champion.
Yet he kept doing it. In 1980 alone he deregulated banking, trucking, and the railroads, calling it “the capstone of my efforts… to get the federal government off the backs of private industry.”
Ronald Reagan beat him that November… and in his second week in office finished Carter’s phase-out of federal price controls on oil, and continued deregulation from there. Two presidents who agreed on practically nothing agreed on boosting competition.
Nothing on that scale has happened since. For forty years the pile of rules has kept growing, and you pay for it every day.
Start with the airlines, where the ban on competition outlived the Board. No foreign airline may carry passengers between two American cities. Europe opened its domestic routes to airlines from other EU countries in 1997. Comparable fares there are well below America’s.
Under the Jones Act, a 1920 law, anything shipped between two American ports must travel on an American-built ship owned and crewed by Americans. Fewer than 100 large oceangoing ships qualify.
No American yard has built a liquefied natural gas tanker since 1980, so no American-built ship can carry Texas gas to Boston. New England consequently buys its winter gas from overseas instead.
Ironically, after hurricanes pummeled Puerto Rico in 2022, the government suspended the Jones Act so a foreign tanker could bring diesel to the island; this suggests that politicians already know how cumbersome and expensive the Jones Act is.
Hospitals need permission to exist, too. In 35 states medical facilities can’t open or expand without state approval, and states with these laws have about 30% fewer hospitals per person.
The National Association of Home Builders found that regulation adds about $132,000 to the price of a new home. Hardly any of that has to do with safety or quality.
Want to build a power line, a pipeline, or a mine? Consulting firm McKinsey estimates $1.5 trillion of investment is stuck in federal permitting.
Want to cut hair? That takes nearly a year of state-mandated training. One in five American workers now needs government permission to do their job.
And right now the government is keeping cheaper cars out. Chinese companies build a decent mid-size SUV for around $20,000 that American automakers would have to compete with. So Chinese cars face a 100% tariff, and the Commerce Department, citing national security, banned cars with Chinese-linked software. Americans pay more as a result.
The pattern is hard to miss: wherever the government gets involved, prices go up.
It has happened every single time the government stepped in to make something more affordable – education, housing, child care, healthcare.
Competition and technology are the only forces that have EVER brought prices down for good, and almost every rule in that pile exists to stop one or the other.
America got rich on competition yet has spent forty years legislating it away.
A real overhaul of the rules would do for the whole economy what Carter’s law did for airfares. Clear them away and the country will build more, make more, start more businesses…
None of this is difficult. Jimmy Carter did it with a signature. But the politicians refuse, and waiting on them is not a plan.
And that’s exactly why it makes sense to have a Plan B.
To your freedom,
James Hickman
October 12, 2026
~ Addendum ~
Silver as Refusal: Opting Out of Their Game
 That is why silver – and gold, and productive real assets – are no longer just “investments” in this cycle. They are acts of refusal.
Refusal to store your life’s work in a digital IOU that can be inflated away, frozen, “bailed in,” or conveniently redefined in the next crisis. Refusal to let a class of professional looters dictate what is “safe” while they front‑run you into every bubble and then socialize the losses. Refusal to accept that the only role you are allowed to play in this grand experiment is the last, broke bagholder.
They all hate you and could not care less if you suffer and die horrible deaths, as long as they got rich. They have told you this, not in speeches, but in budgets, in policies, in the cold arithmetic of who gets saved and who gets sacrificed.
 So the question is not whether $100, $240, or $1,000 silver is “too high.” The question is: how much longer are you willing to let a proven mafia be your counter-party?
Because the structural setup for silver is not just bullish. It is a verdict. And when it is finally delivered, you will either own real metal – or a fading IOU from people who have already explained, in excruciating detail, exactly what your life is worth to them.
~ Plan B ~
[Got physical… close at hand?]
Let’s do something about that…
While there’s no guarantee on any investment, it is clear we have entered a period of great economic uncertainty. In recent economic news, several banks and major financial institutions have filed for bankruptcy leading our country into what is likely a recession period. The US dollar is losing significant value caused in part by monetary inflation, overspending, and fading market confidence. Some economists speculate that the US will consider a centrally controlled, government issued, cryptocurrency as a means to promote Modern Monetary Theory.
Throughout history, as fiat currencies have come gone, gold has stood the test of time again and again, and there’s reason why… Give Gold – and Silver – a Look in These Uncertain Times.
Always and again the magic of money presents us with problems. These problems change constantly. Time after time experience teaches us that there is no universally-valid system by means of which monetary problems may be solved. Every new situation demands new deliberations, new measures, new insights, new ideas. Each of these ideas must be informed by and subservient to the sole and single purpose of maintaining the soundness of the currency. ~ Hjalmar Schacht
Seeking out the most efficient and most secure route to owning gold, and converting it into widely-accepted currency, is the next best thing to enjoying gold-backed currency.
In a world of central bankers hell-bent on devaluing your savings you need your own private gold standard.
Call us!
Kettle Moraine, Ltd.
P.O. Box 579
Litchfield Park, AZ 85340
602 – 799 – 8214
kettlemoraineltd@cox.net